English
 简体中文
In the first three quarters of 2026, our country's imports of Thai rubber wood showed a trend of "volume shrinkage and price increase, and the average price rose quarter by quarter".
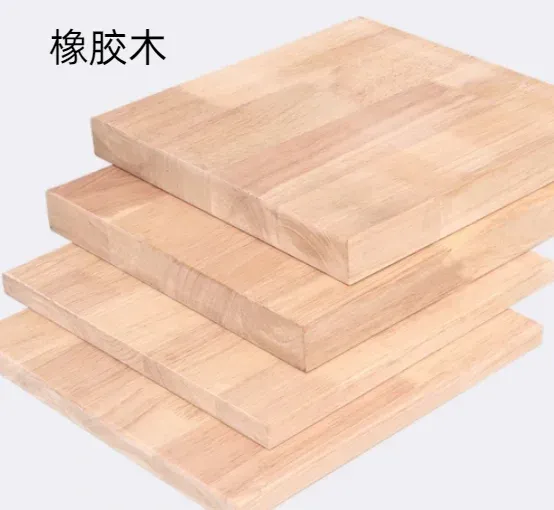
Customs data show that in the first three quarters, our country's imports of rubber wood from Thailand totaled 3.096 million cubic meters, down 4.4% year-on-year; the cumulative import amount was 874 million US dollars, an increase of 6.8% year-on-year, and the average import unit price increased by 12% year-on-year.
In the first quarter, imports were 1.047 million cubic meters, down 6% year-on-year; in January, the arrival scale of 314,000 cubic meters was maintained, and in February, it fell sharply to 263,000 cubic meters, and rebounded to 471,000 cubic meters in March at the end of the quarter.
Market analysis pointed out that the energy shortage in southern Thailand and the cancellation of logging subsidies have begun to substantially compress supply elasticity in the first quarter, with some processing plants reducing production by 30%, but domestic buyers have not yet fully accepted the new price hub, and procurement behavior has shown the alternating characteristics of "tentative - wait and see - centralized replenishment".
The second quarter: imports of about 1.046 million cubic meters, the year-on-year decline narrowed to about 4.8%, but the average price increase jumped from 9.1% in the first quarter to 11.7%. Among them, the average price increase in May reached a peak of 13% in the year, and remained at a high of 11.7% in June.
The analysis shows that Thailand officially entered the rainy season in mid-May, with continuous rainfall covering the main producing areas in the east and south, causing a significant decrease in the efficiency of logging and cross-regional transportation. At the same time, under the double pressure of increasing difficulty in obtaining raw materials and rising costs such as energy, processing plants are willing to raise prices, and domestic importers are obviously cautious in the face of rising CIF prices. Imports contracted continuously from May to June, and the weak signal on the demand side began to be released.
Third quarter: imports of about 1.002 million cubic meters, down about 5.7% year-on-year, the decline compared with the second quarter expanded; the average price rose by about 12.1% year-on-year, but narrowed significantly compared with the second quarter. July imports 364,000 cubic meters, is still stable; in August fell sharply to 323,000 cubic meters, down 11.2% month-on-month, down 8% year-on-year, a new monthly decline in the year; in September rose slightly to 306,000 cubic meters, an increase of only 3.1%.
Heavy rains and floods in Thailand's main producing areas further tightened supply expectations, despite domestic spot prices being supported by cost bottoms; however, there was a lack of large orders in the downstream home improvement, building materials and furniture manufacturing fields, and factories generally adhered to the "just use and buy" strategy. The acceptance of high prices was limited, and the market lacked the incremental impetus to promote transaction volume.
Combining the current situation of tight supply in Thailand and relatively stable domestic demand in the first three quarters: the supply side is constrained by the insufficient release of production capacity in Thailand, and the import volume lacks support; although the demand side does not contract significantly, it also lacks upward elasticity. Under the two-way effect, the market is difficult to reverse the trend. Timber Home predicts that from the fourth quarter of 2026 to the beginning of 2027, the market will likely continue the pattern of "difficult import volume and high price operation".